

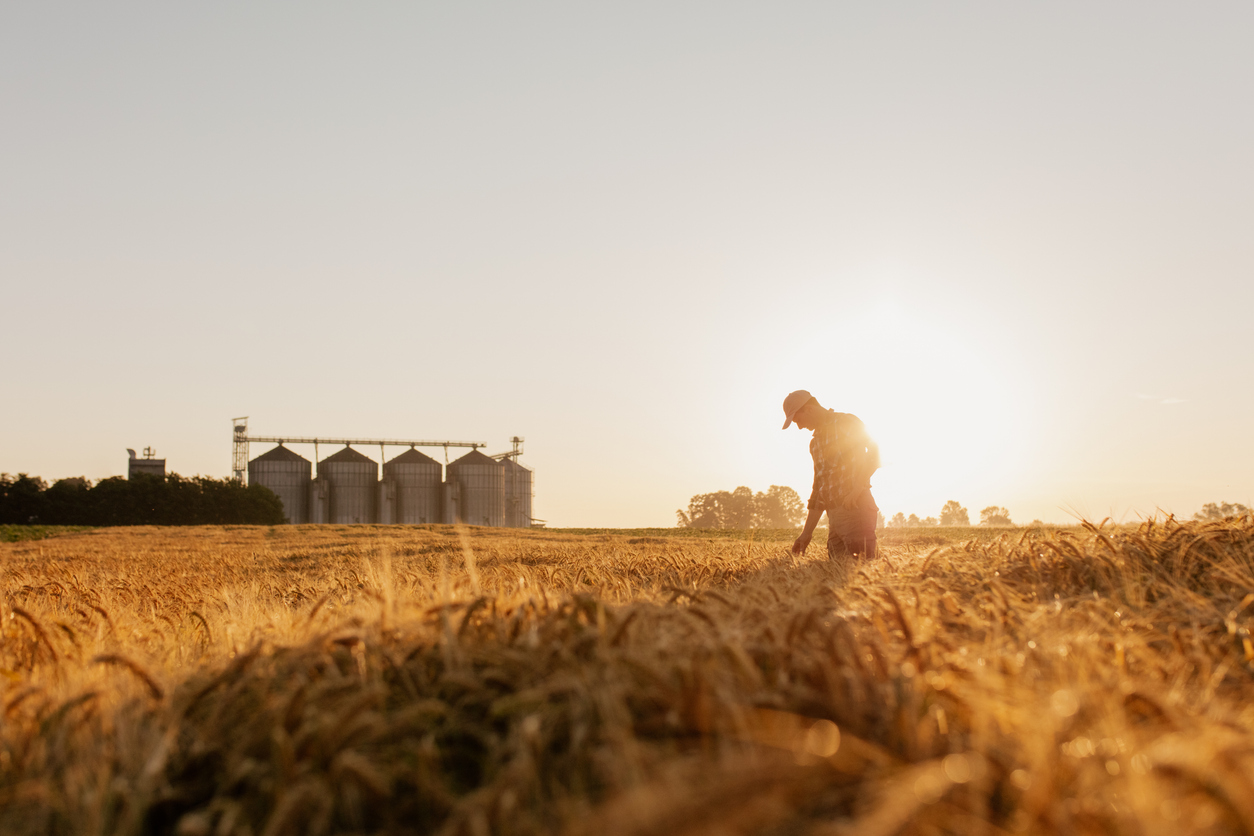
Last week, July 30th, I finished The Good Earth by Pearl Buck. This was her magnum opus, and a very good read. At one point, I imagine it made any number of ‘required reading’ lists for certain American students. However, I doubt it does any longer.
At the start of the book, the main character, Wang Lung, is an impoverished farmer who marries a slave woman named O-Lan. By the end, through hard work and some morally-questionable decision-making, he has become the richest man in town.
While the story is set in rural China roughly a century ago, there is much the modern reader should still be able to recognize. To be sure, societal norms change over time and vary from culture to culture. However, inherent human nature arguably doesn’t.
‘Human nature’ can take on many guises since there are any number of humans. However, the core of the concept is mostly universal. This being self-preservation. There is a name for those who consistently put others ahead of themselves –– they’re called saints.
Now, you might be wondering what in the good earth does this have to do with the U.S. economy and financial markets. Shoot, I am beginning to wonder myself, and I am curious to see where this goes.
In the book, there is a conspicuous lack of government. So much so, the reader is left to wonder exactly when the story takes places. Is it the end of the Qing dynasty? The start of the Warlord Era? I mean who is in charge here?
As the following quote in Chapter 12 of The Good Earth suggests, the characters appear to be ambivalent and ignorant about government in general.
“..[O]nce when Wang Lung heard a young man… [say] that China must have a revolution and must rise against the hated foreigners, Wang Lung was alarmed and slunk away, feeling that he was the foreigner against whom the young man spoke with such passion. And when on another day he heard another young man speaking… and he said… that the people of China must unite and must educate themselves in these times, it did not occur to Wang Lung that anyone was speaking to him.” (1)
It isn’t just the ignorant Wang Lung who seems out of touch. It seems to be everyone. Apart from the elite few, everyone in the book is basically living by their wits, through back-breaking work, thievery or some sort of connivance.
However, it should not be lost on anyone that the harder Wang Lung and O-Lan worked, the wealthier they became. Further, at no point in the book, from what I remember, did anyone expect a faraway bureaucratic entity to provide economic opportunity.
Of course, the obvious retort would be something along the lines of: “well, Norris, the book is about dirt farmers in an undeveloped country at the turn of the 20th century. Of course, they didn’t have the same institutions we have today in the United States. But are you saying they are better off without them, because clearly, they aren’t?”
Admittedly, the inference might seem to be there. However, that is not my argument.
You see, the folks in the book who depend on charity, whether from strangers or family members, don’t seem to advance economically. Nor do workers who don’t plan and save for the future. They all seem to be stuck in a state of stagnant economic development.
To be sure, Wang Lung and O-Lan pilfered from a wealthy merchant’s house in the city to the South. That was certainly far from honorable. However, what did they do with that money? Those jewels? Did they waste it on things which are immediately consumed or rapidly depreciate? On amusements of various sorts? Were they careless with it?
No. Wang Lung bought additional land and implements to make his farm more productive. In essence, he invested his money in assets which would likely appreciate more rapidly. Those things which would increase the size of his balance sheet and income statement, although he would have had no idea what such things were.
You see, even in undeveloped economies, some people ‘get it.’ Hard work, thrift and ownership seem to be part of a somewhat universal recipe for economic well-being. In fact, it is difficult for me to imagine a society generating and maintaining any sort of meaningful wealth without those things.
Inherent in this is the assumption that people are able to keep what they earn, or at least a reasonable amount, which will incentivize them to continue working hard. Economic theory suggests that as incentives diminish, individuals may alter their work effort or seek alternative opportunities. They will either work less or find some other way to make money.
No? Fair enough. Let me ask you this. Will you come over and mow my yard on Saturday for, say, $25? No? That isn’t worth your time? Okay, how about $1,000, cash money? I don’t know you and you don’t know me. Oh, that sounds good? Okay, now, how about $25 cash money and a $975 gift made in your honor to a charity of my choice?
What? Where are you going? Come back here.
This isn’t a difficult concept to understand. But this basic economics still baffles many Americans. How else can you explain recent proposals for city-operated grocery stores, which raise broader economic questions about incentives, capital allocation and long-term financial sustainability? (2)
The largest city proposing such a scheme has “total projected indebtedness against the (debt) limit” of roughly $96.3 billion as of July 1, 2026. (3) With an estimated population of 8,584,629 (as of July 2025), that works out to be roughly $11,200/person. (4)
Intuitively, it would seem as though this governing is not terribly focused on generating a profit and thereby creating wealth. If this is the case, what will the incentive be to efficiently run these proposed grocery stores? That is if money isn’t an apparent concern?
Further, when ownership incentives are weakened, why would anyone care if capital is allocated correctly? If goods and services get to the appropriate places at the right times and for the correct amount of money?
Of course, they likely wouldn’t. This, then, would result in one of three outcomes:
1) The city can shut the inefficient operation down
or
2) The city could subsidize the inefficient operation with even more at the expense of other services
or
3) Try to run it to make a true profit
After all, you can only prop up phony profits and unproductive industries for so long. Just ask Gorbachev. (5)
This isn’t rocket science. You don’t need a calculator, slide rule or a PhD or MBA to figure this out, because ‘basic economics’ is also inherent human nature. Shoot, Pearl Buck had undergraduate and master’s degrees in English literature.(6) That is all the way over on the other side of the campus from a business degree.
However, she created a character like the ignorant Wang Lung who ‘got it,’ and was/is arguably better equipped to understand basic economic incentives than many people might assume.
So, in the end, as I was closing The Good Earth the other night, I came to the following conclusions. First, I really enjoyed the book. Second, just because you are ignorant doesn’t mean you are dumb. Third, just because you are educated doesn’t mean you are smart. Fourth, I have a really strange way of thinking.
Thank you for your continued support. As always, I hope this newsletter finds you and your family well. May your blessings outweigh your sorrows on this and every day. Also, please be sure to tune into our podcast, Trading Perspectives, which is available on every platform.
John Norris
Chief Economist
Sources
- LitCharts – The Good Earth Quotes. Accessed July 31, 2026.
- Business Insider – 30% Savings and an NYC Private Label: What to Know About Mamdani’s City Run Grocery Stores. July 29, 2026.
- New York City Comptroller – Annual Report on Capital Debt and Obligations, Fiscal Year 2026. December 1, 2025.
- United States Census Bureau – New York City, New York Population Estimates. Accessed July 31, 2026.
- Investopedia – USSR Economic Collapse: Key Events and Causes. February 19, 2026.
- National Women’s History Museum – Pearl S. Buck. Accessed July 31, 2026.
About Common Cents:
Please note, nothing in this newsletter should be considered or otherwise construed as an offer to buy or sell investment services or securities of any type. Any individual action you might take from reading this newsletter is at your own risk. My opinion, as well as those of our Investment Committee, is subject to change without notice. The opinions expressed herein are not necessarily those of the rest of the associates and/or shareholders of Oakworth Capital Bank or the official position of the company itself.
Opinions and forward-looking statements are subject to change without notice and may not come to pass. Past performance is not indicative of future results. References to market indices are for illustrative purposes only. Index performance does not reflect the deduction of fees or expenses, and individuals cannot invest directly in an index. Political and geopolitical events are referenced for general context and do not represent a recommendation or prediction regarding any specific investment outcome. Links to third party articles are provided for informational purposes only. Oakworth Asset Management LLC does not control, endorse or adopt the content, opinions or recommendations expressed on third party websites. Such content may be dated and may not reflect current market conditions. Third party information is believed to be reliable but has not been independently verified. Readers should evaluate the information independently. Any reference to specific securities is provided for informational and illustrative purposes only and should not be considered a recommendation to buy, sell, or hold any particular investment. It should not be assumed that any such securities discussed were or will be profitable.
About Oakworth:
Oakworth Capital Bank, Member FDIC, Equal Housing Lender, provides commercial and private banking, wealth management and advisory services. Advisory Services, including investment management and financial planning, are offered through Oakworth Asset Management LLC, a registered investment advisor. Oakworth Asset Management LLC is owned by Oakworth Capital Bank. Investment products and services offered via Oakworth Asset Management LLC are independent of the products and services offered by Oakworth Capital Bank, and are not FDIC insured, may lose value, have no bank guarantee, and are not insured by any federal or state government agency. Because of the ownership relationship and involvement by Oakworth Asset Management LLC associates with Oakworth Capital Bank, there exists a conflict of interest to the extent that either party recommends the services of the other. For additional information about Oakworth Asset Management LLC, including its services and fees, visit adviserinfo.sec.gov.